- Beyond Basic OCR: IDP classifies, extracts, validates, and routes loan documents for faster, more accurate processing.
- Lower Processing Costs: Automated document handling reduces manual reviews, errors, and operational costs across lending workflows.
- Smarter Loan Audits: IDP supports underwriting, compliance, and QC through automated checks and human exception reviews.
Loan files rarely stay static from application to closing.
CFPB research covering about 50,000 mortgages found that almost 90% had at least one revision during origination. About 62% received a revised Loan Estimate, while 49% received a corrected Closing Disclosure.
Every revision can trigger document checks, data comparison, validation, and compliance review. That work adds time when teams rely on manual entry or OCR alone. Intelligent document processing for loans addresses this problem by classifying documents, extracting key fields, validating data against rules, and routing exceptions to reviewers. This blog explains how this workflow operates across the loan lifecycle, where it fits by loan type, and what lenders can measure in accuracy, cycle time, and cost per loan.
What Is Intelligent Document Processing for Loans?
Intelligent document processing for loans uses AI to read, classify, extract, validate, and route data from lending documents. It can process structured and unstructured files such as applications, bank statements, tax forms, pay stubs, disclosures, appraisals, and closing documents.
How IDP Differs from OCR in Lending
OCR, or Optical Character Recognition, converts printed or handwritten text into machine-readable text, while IDP goes further. It identifies the document type, finds relevant fields, understands tables and layout, applies lending rules, compares values across documents, assigns confidence scores, and sends uncertain results for review. OCR creates readable text. IDP turns loan documents into usable data for lending workflows.
Why Lenders Are Adopting IDP Now
Lenders are under pressure to process files faster without adding the same amount of manual work. IDP reduces repetitive document handling while giving operations, underwriting, and compliance teams structured data they can review, verify, and act on faster.
Rising Loan Volumes and Staffing Constraints
Loan volume can rise faster than operations teams can hire and train reviewers. IDP absorbs document intake, classification, extraction, and comparison work, so staff can spend more time on exceptions and credit decisions. This gives lenders more processing capacity without matching every increase with added manual work.
Compliance and Audit-Trail Pressure
Loan files pass through rules, disclosures, verification steps, and quality checks. IDP can record extracted values, rule results, confidence scores, changes, and reviewer actions, giving teams a clearer record of how each result was handled. That record can support QC and audits.
Borrower Expectations for Faster Decisions
Borrowers expect updates and fewer requests for the same information. Automated document processing can reduce waiting between document submission and review, helping lenders move files to underwriting or closing faster while keeping human review available for uncertain cases. Faster handling can also reduce back-and-forth with borrowers.
How Intelligent Document Processing Works Across the Loan Lifecycle
IDP connects document intake with lending decisions. The workflow moves from file recognition to extraction, validation, and exception review, creating structured data for downstream underwriting, QC, servicing, and compliance systems.
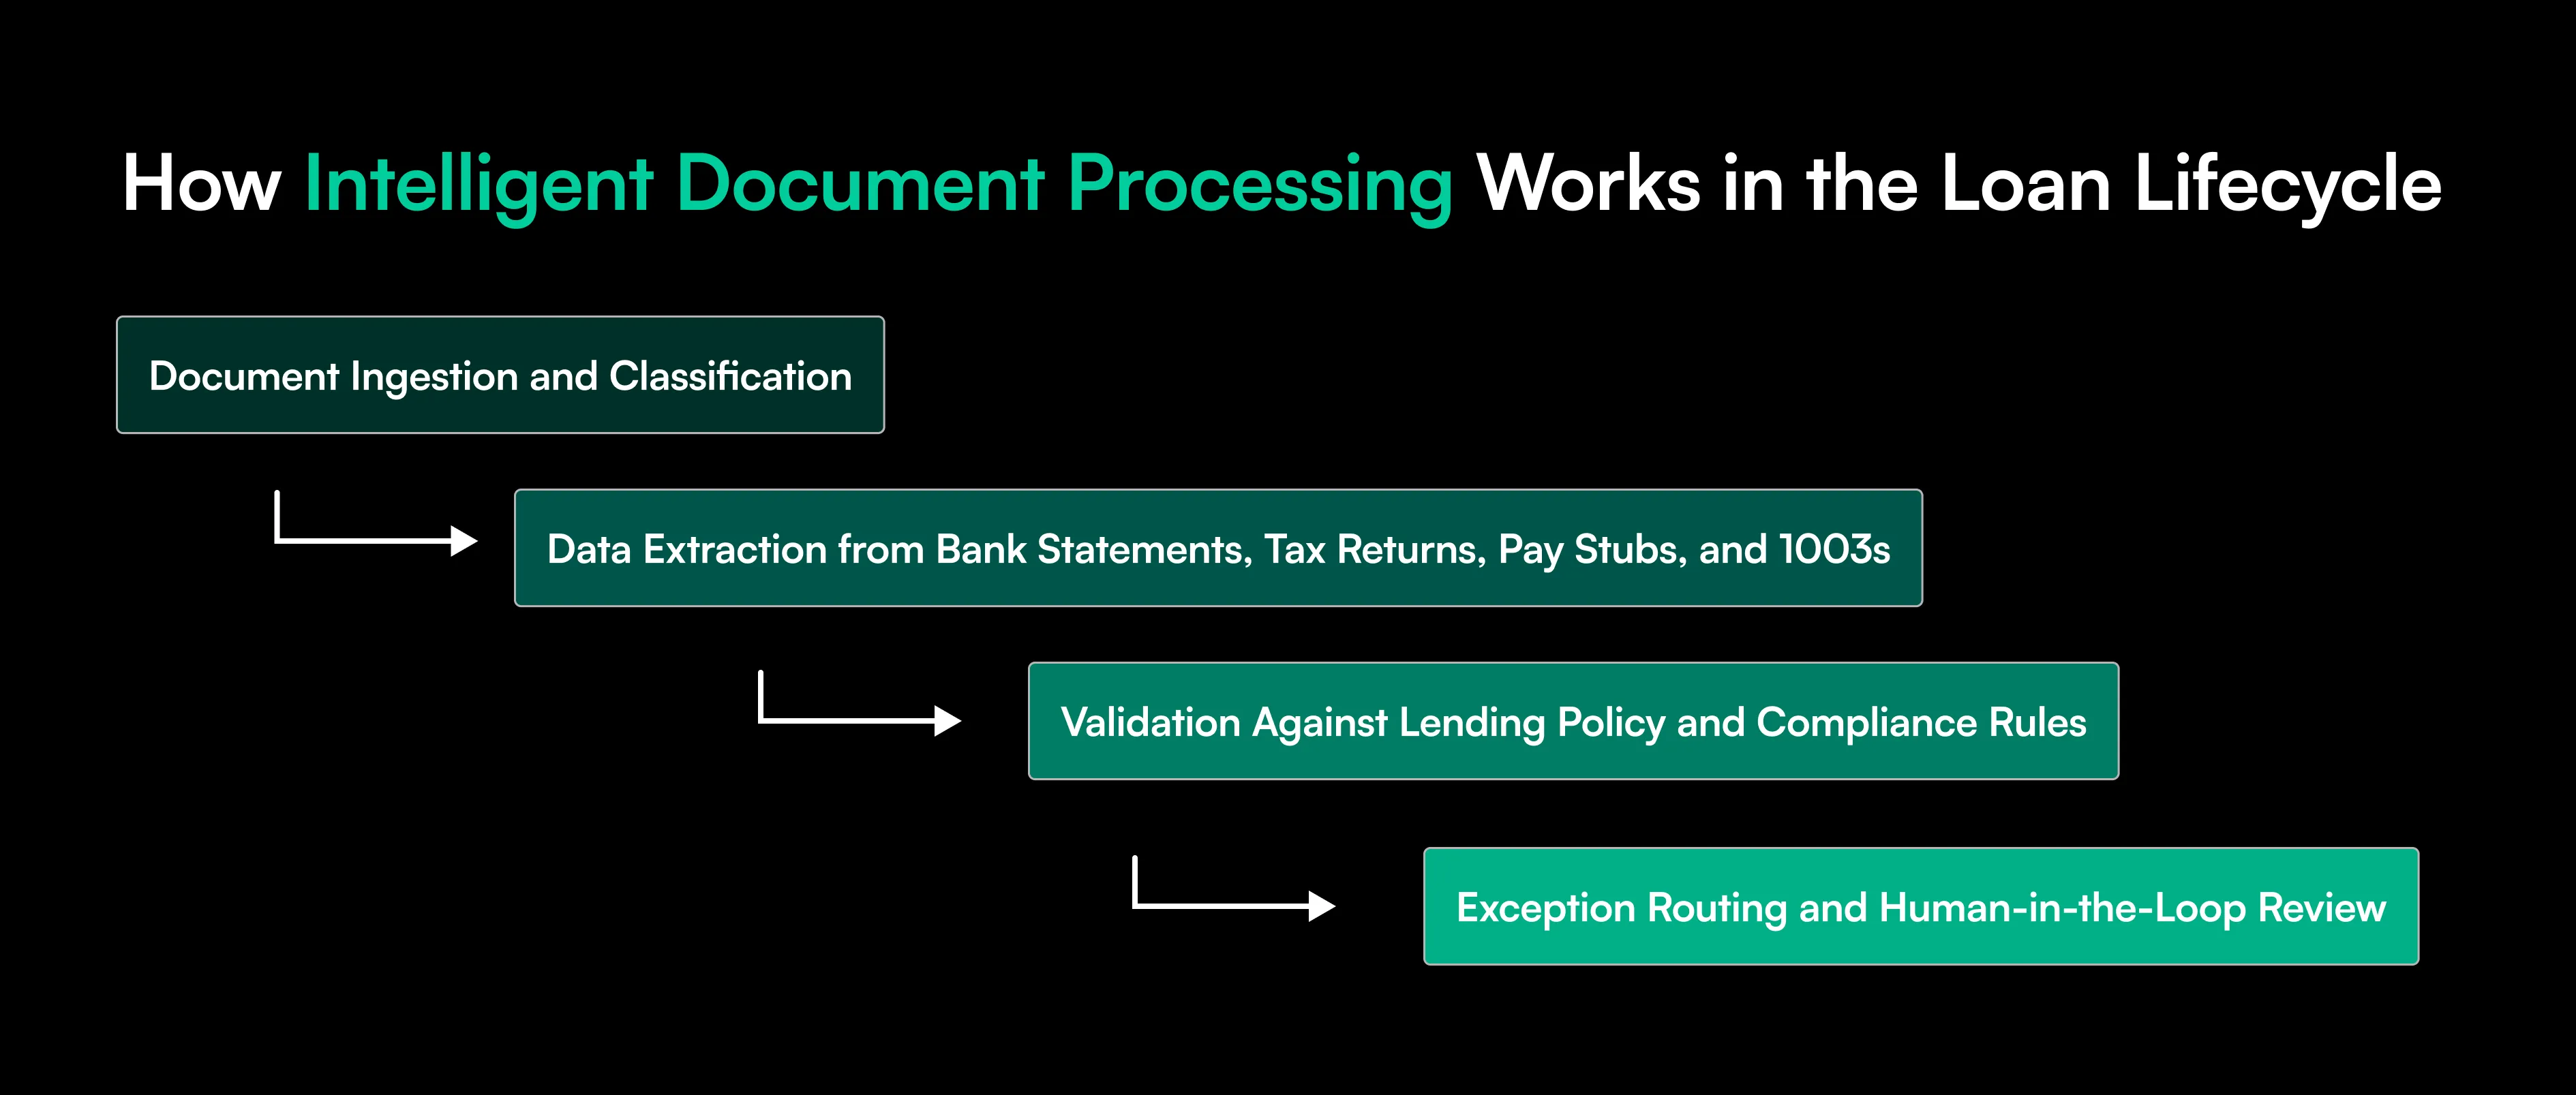
Document Ingestion and Classification
Documents can enter through borrower portals, email, uploads, APIs, scanners, or LOS workflows. IDP identifies each file, separates loan packages, detects document types, and organizes pages before extraction begins. This gives downstream processes a consistent structure.
Data Extraction from Bank Statements, Tax Returns, Pay Stubs, and 1003s
The system extracts fields such as income, employer details, account balances, liabilities, borrower information, dates, and loan terms. It can also capture tables and values across long files without relying on a page position. Confidence scores show which results may need review.
Validation Against Lending Policy and Compliance Rules
Extracted data can be checked against business rules, required-document lists, calculation logic, and values from other loan documents. A mismatch between income figures, missing pages, or inconsistent borrower details can be flagged before the file moves forward. Lenders can also apply product, investor, or internal policy checks.
Exception Routing and Human-in-the-Loop Review
IDP does not need to treat every field the same. High-confidence results can continue automatically, while low-confidence fields or rule failures can enter a review queue. Reviewers correct only items that need attention. Their decisions can feed quality controls and model-improvement workflows, reducing repeated manual checks across files.
Intelligent Document Processing for Different Loan Types
The same document-processing layer can support different lending products, but the documents, rules, and review steps change by portfolio. IDP can adapt extraction and validation workflows to the specific data, policy checks, and supporting evidence required for each loan type.
Mortgage Origination and Servicing
Mortgage teams process files across application, underwriting, closing, post-close QC, and servicing. IDP can extract borrower, income, asset, property, disclosure, and closing data, then compare information across documents. It can identify missing documents, duplicate pages, and conflicting values before they create rework.
Commercial and SME Lending
Commercial and SME files include financial statements, tax returns, bank records, ownership documents, leases, and supporting schedules. IDP can organize these files, capture financial data, and flag missing or inconsistent information for analyst review. This lets credit teams spend less time searching documents and more time evaluating the business case.
Consumer and Personal Loans
Consumer lending often depends on decisions across smaller files. IDP can process identification, income, bank, application, and supporting documents, then send structured values into credit and decision systems. This reduces manual data entry while keeping exception review available for cases that fail policy or confidence checks.
Measurable Benefits and ROI
The value of IDP appears in lender measures: defect rates, processing time, reviewer effort, and production cost. Strong ROI comes from removing repeated manual work while keeping controls in place.
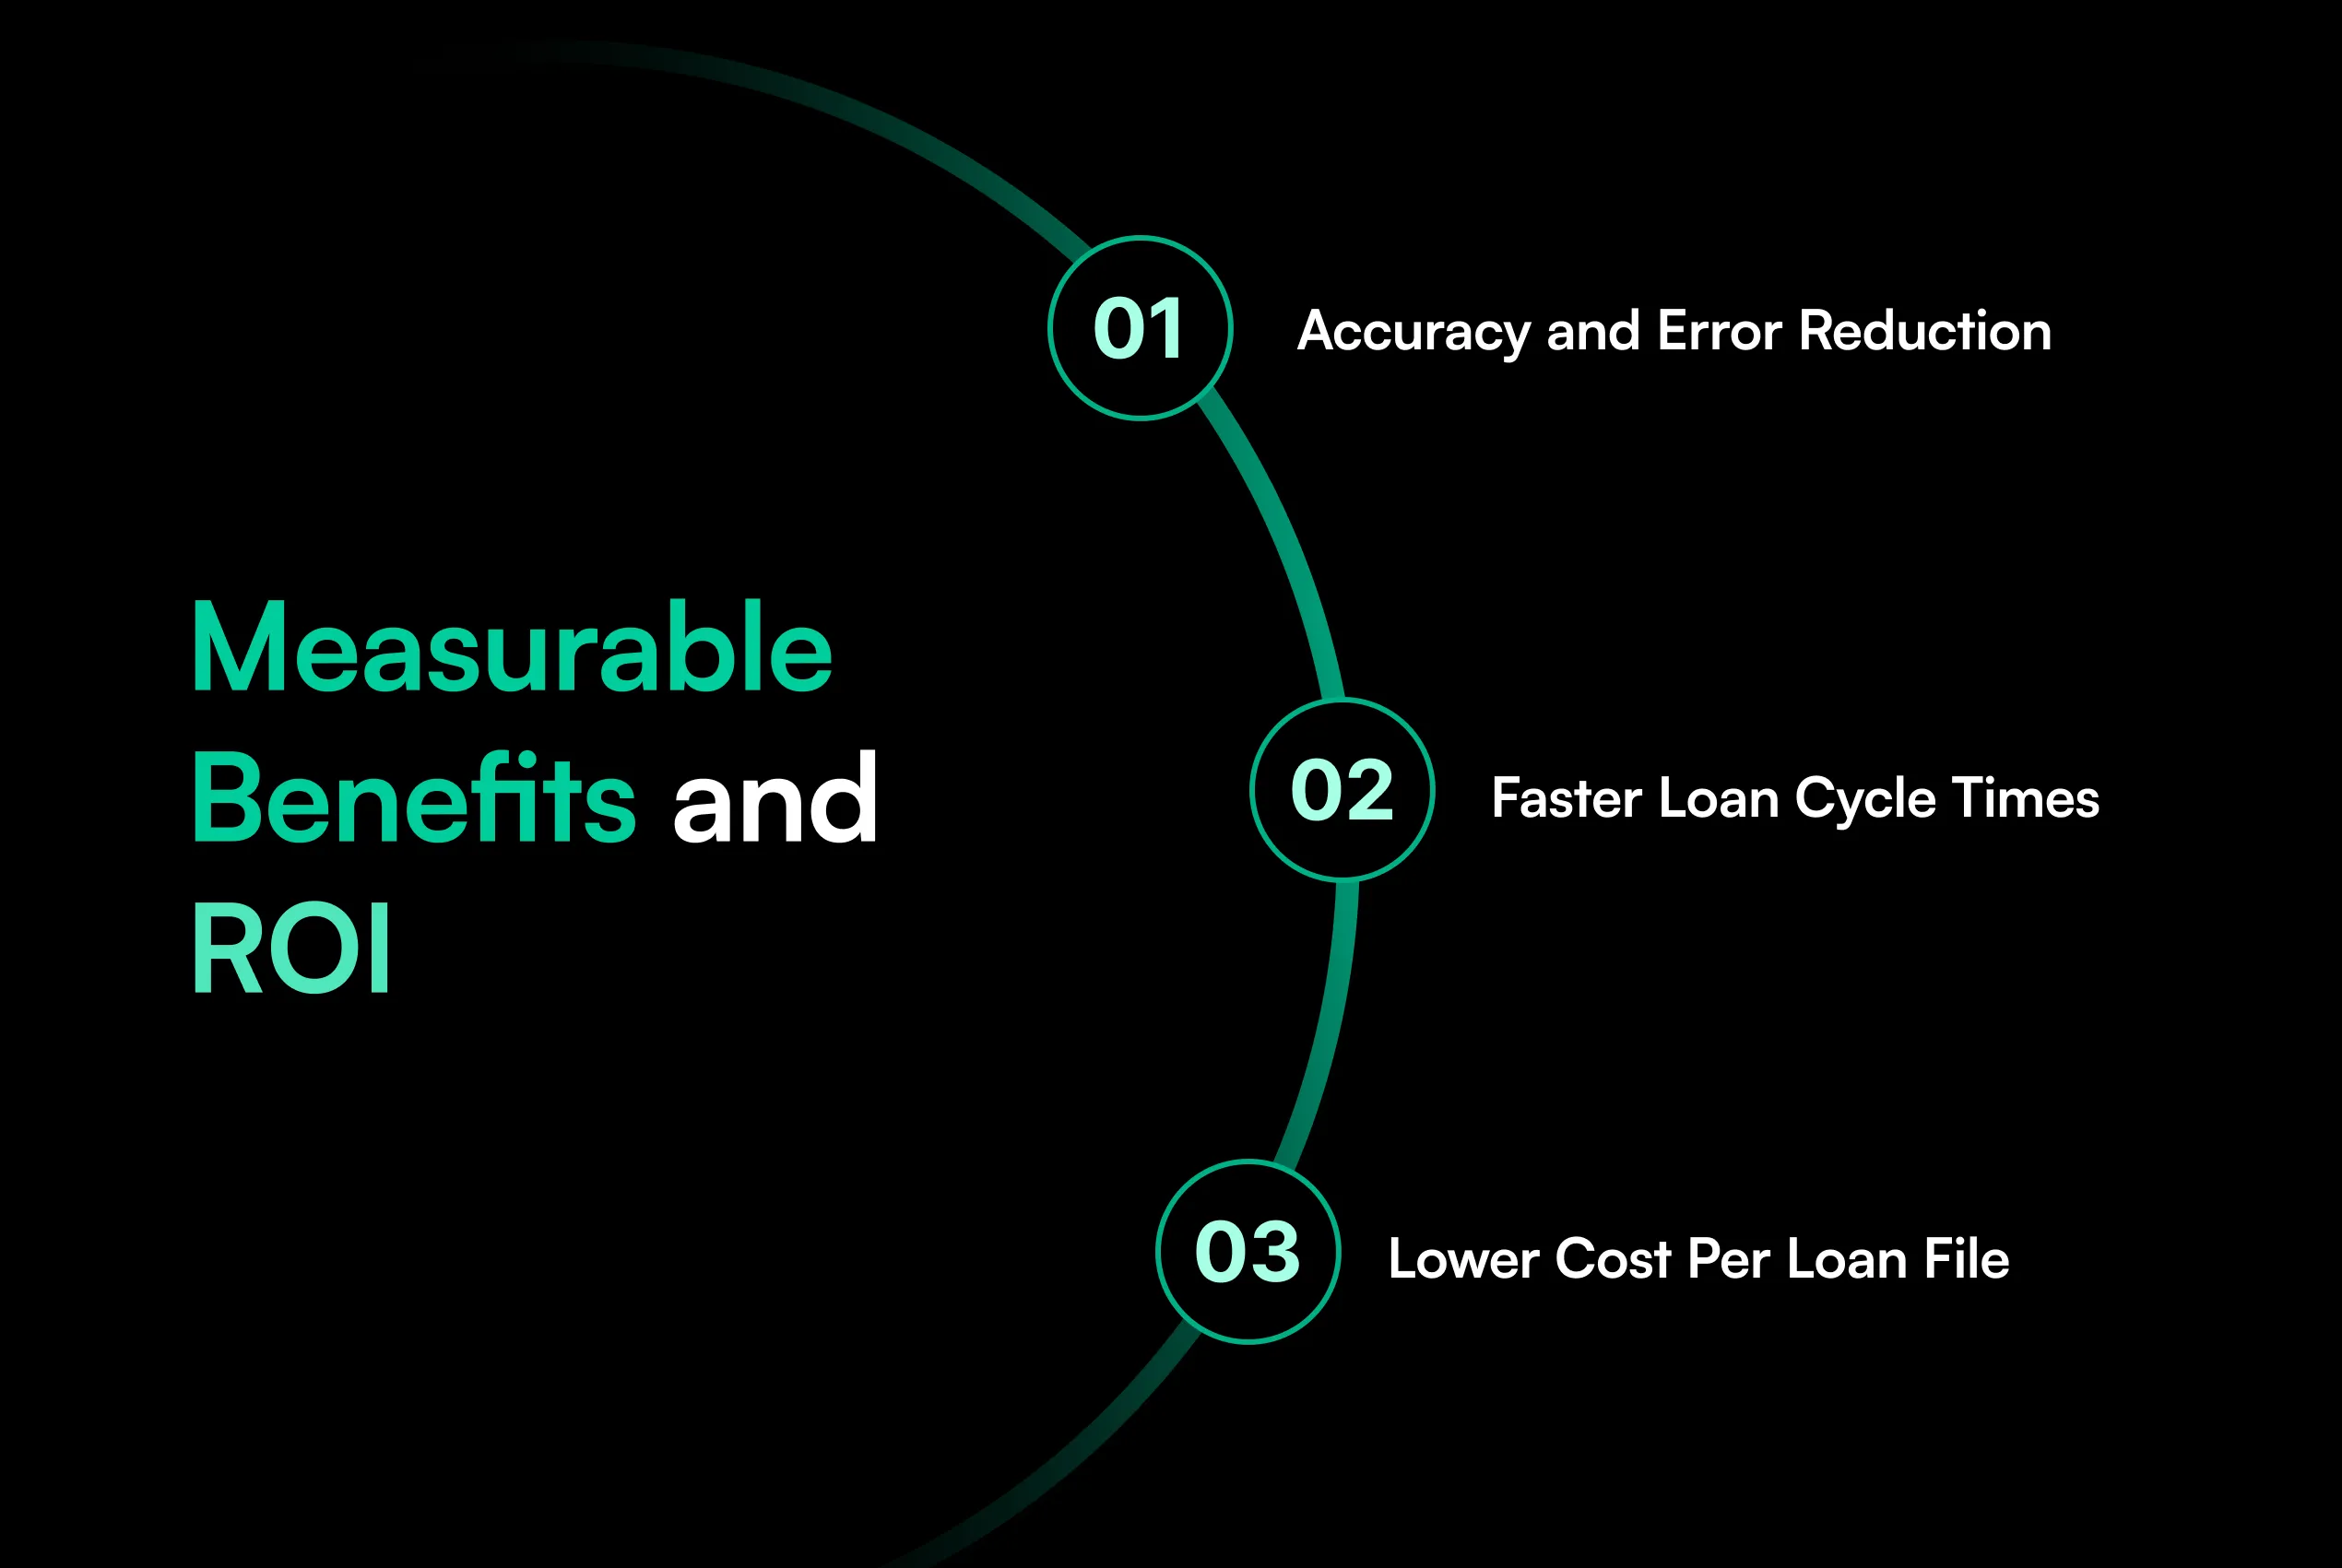
Accuracy and Error Reduction
Freddie Mac found a 4.5% defect rate for loans using its Asset and Income Modeler alone, compared with 9.6% for loans without the technology offerings in its analysis. The finding is specific to Freddie Mac’s study, but it shows how automated data and verification tools can significantly reduce defects when every amount and number matters.
Faster Loan Cycle Times
Automated classification, extraction, validation, and routing reduce the time between receiving a document and making its data available for review. FHFA also cites Freddie Mac research showing digital mortgage processes can save up to 18 days in closing cycle time. IDP supports that workflow by removing document-level delays.
Lower Cost Per Loan File
FHFA reports that lenders with higher digital-solution use originated loans at about 14% lower production cost, equal to roughly $1,700 per loan. IDP can contribute by cutting data entry, repeated document checks, rework, and reviewer time spent on already-correct data.
Integration with Loan Origination Systems (LOS) and Compliance Tools
IDP delivers more value when it connects directly with systems lending teams use. Integrations with platforms such as Encompass, Blend, and Byte can move extracted loan data into existing workflows instead of asking staff to copy values between screens. The same approach can connect with compliance, QC, underwriting, and servicing tools through APIs or exports. This reduces duplicate entry, shortens handoffs, and keeps document evidence linked to the loan record.
How Infrrd Provided Intelligent Document Processing for Loans
Infrrd applies intelligent document processing for loans that goes beyond basic extraction. Its mortgage deployments have processed 12M+ pages, extracted 170+ complex data points, achieved over 95% accuracy, and reduced human error by 97%.
MortgageCheckai provides the document processing and QC layer. It can split, classify, stack, extract, validate, compare document versions, identify missing files, and prepare loan data for pre-fund and post-close review.
Ally adds an agentic audit layer on top of that data. It applies mortgage-specific audit logic, runs calculations and rule checks, compares information across the loan file, flags exceptions, and prepares findings for human review. Ally can handle up to 80% of the repeatable audit workload while auditors retain judgment and final approval.
Together, MortgageCheckAI and Ally take IDP from document extraction into loan review, QC, and audit. They can connect with LOS and compliance workflows, reducing manual data transfers while keeping human reviewers in control of exceptions and final decisions.
Conclusion
Intelligent document processing for loans moves lenders beyond OCR-only document capture. OCR can make text readable, but lending teams still need to identify documents, locate fields, compare values, apply rules, manage exceptions, and record review activity. IDP brings those steps into one processing flow.
That matters because loan files change repeatedly, and each change can create another review task. A well-integrated IDP workflow can reduce manual entry, surface issues earlier, and send cleaner data into underwriting, compliance, QC, and servicing systems. The goal is practical: process loan documents with less repetitive work while improving speed, accuracy, traceability, and operating cost.
Frequently Asked Questions
What is intelligent document processing for loans?
Intelligent document processing for loans uses AI to classify lending documents, extract key data, validate results, and route uncertain fields or exceptions for human review.
How is IDP different from OCR for loan processing?
OCR converts text into machine-readable characters. IDP adds document classification, field extraction, validation, confidence scoring, business rules, and exception handling for lending workflows.
Which loan documents can IDP process?
IDP can process applications, bank statements, pay stubs, tax returns, IDs, appraisals, disclosures, closing documents, financial statements, and many other supporting loan files.
Can IDP integrate with a loan origination system?
Yes. IDP platforms can connect with loan origination systems through APIs, file exchange, or native integrations so extracted data moves into existing lending workflows.
Does IDP replace underwriters or loan reviewers?
No. IDP handles repetitive document work and surfaces exceptions. Underwriters, QC teams, and reviewers still make lending, compliance, and risk decisions that require judgment.
How does IDP improve loan processing accuracy?
IDP applies extraction models, validation rules, cross-document checks, and confidence scores. It can flag missing, conflicting, or uncertain data before the file moves forward.
Can IDP support mortgage compliance and audits?
Yes. IDP can record extracted values, rule results, document versions, confidence scores, and reviewer actions, creating traceable evidence for QC, compliance, and audit workflows.
How can IDP reduce loan processing costs?
IDP reduces manual data entry, document sorting, repeated comparisons, and unnecessary reviews. Lower reviewer effort and fewer corrections can reduce the operating cost per loan.
Can IDP process commercial and consumer loans as well as mortgages?
Yes. The same core workflow can support mortgage, commercial, SME, personal, and consumer loans by changing document types, extraction fields, validation rules, and review logic.
What should lenders look for in an IDP platform?
Lenders should assess document coverage, extraction accuracy, confidence scoring, validation rules, human review, audit trails, integration options, security controls, and measurable production performance.